Buying a Manufactured Home in Canada: Financing, Land and Costs
A manufactured home can cost less than a site-built house, but the financing depends on one question: is the home fixed to land you own, or movable on a lot you rent?
- Rules checked November 2, 2026
- By Krish Paul
- 5 min read
On this page
This guide explains the two CMHC financing routes, what insurance costs on a $300,000 home, and what to check on a leased lot.
The short answer
You can finance a manufactured home in Canada, but the type of loan depends on whether the home is fixed to land. A home on a permanent foundation can get a regular mortgage with CMHC insurance and as little as 5% down. A movable home that is not fixed to land is financed with a chattel loan instead.
Both routes run through the CMHC Prefab Plus program for prefabricated, modular and manufactured homes. Whether you own the land or lease a lot changes the financing and your monthly costs, so settle that first.
Mobile, manufactured, modular: what the words mean
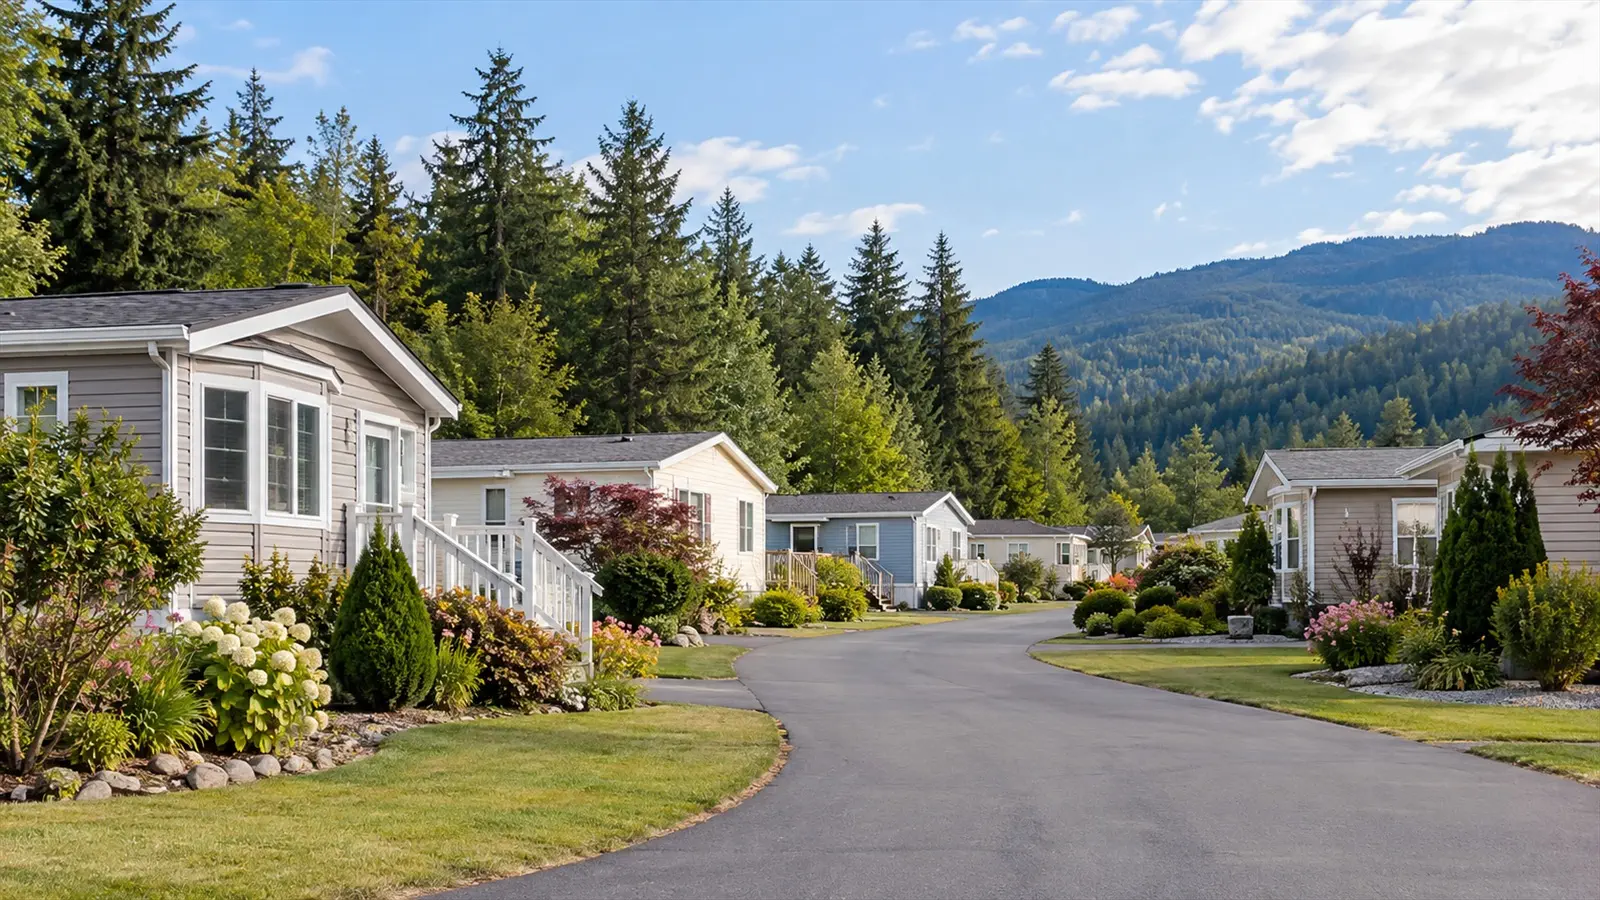
Statistics Canada defines a mobile home as “a single dwelling designed and constructed to be transported on its own chassis and capable of being moved to a new location on short notice.” It may sit on blocks, posts or a pad, with a skirt around the base. Movable dwellings, which include mobile homes, made up 1.3% of occupied homes in the 2021 Census.
Manufactured and modular homes are both built in a factory. The difference that matters for money is not the label but where the home ends up: on a permanent foundation on land, or movable on a lot.
Two ways to finance it
| Permanent foundation on land | Movable, not fixed to land | |
|---|---|---|
| CMHC route | Standard underwriting | CMHC Chattel Financing |
| Loan secured by | A traditional mortgage | A chattel mortgage loan |
| Non-traditional down payment | Possible for 1 to 2 units | Not eligible |
Source: CMHC Prefab Plus. The page notes eligibility depends on borrower criteria, property standards and financing details, and that the information is subject to change.
CMHC Prefab Plus also sets these conditions for homeowner loans: the purchase price or lending value must be below $1,500,000, the maximum amortization is 25 years, and the property must be in Canada, suitable for full-time year-round living and have year-round vehicular access. For 1 to 2 unit homes, loans go up to 95% loan-to-value.
What CMHC insurance costs on a $300,000 home
With less than 20% down, the mortgage needs default insurance. The CMHC premium depends on your loan-to-value ratio and is usually added to the mortgage. Here is a hypothetical $300,000 manufactured home on owned land with a permanent foundation.
| Down payment | Amount down | Mortgage | Premium rate | Premium |
|---|---|---|---|---|
| 5% | $15,000 | $285,000 | 4.00% | $11,400 |
| 10% | $30,000 | $270,000 | 3.10% | $8,370 |
| 15% | $45,000 | $255,000 | 2.80% | $7,140 |
Calculated by script: mortgage x premium rate (for example, $285,000 x 4.00% = $11,400), then re-checked by multiplying each figure directly. Premium rates: 4.00% for 90.01% to 95% loan-to-value, 3.10% for 85.01% to 90%, 2.80% for 80.01% to 85%. Provincial sales tax applies to the premium in some provinces and cannot be added to the loan.
The minimum down payment follows the same FCAC rules as any home: 5% of the first $500,000. See how much CMHC insurance costs for every down payment tier.
Owned land or a leased lot
Many manufactured homes sit in land-lease communities, sometimes called parks. You own the home but rent the lot, and you pay a monthly site fee. That fee is a housing cost like rent, so it affects your budget and how much a lender will approve.
Provinces regulate these sites under their own tenancy laws, and the rules on fee increases, sales and park rules vary. Before you buy, get the lease terms in writing, ask how the site fee has changed in recent years, and ask whether the park must approve a buyer when you sell.
Questions to ask before you buy
- Is it on a permanent foundation?That decides whether you can get a regular mortgage or need chattel financing.
- Do I own the land?If not, what is the site fee, how long is the lease and what are the park rules?
- Is it a year-round home?CMHC requires year-round occupancy and year-round vehicle access.
Steps to buy a manufactured home
- Decide on land. Owned land with a permanent foundation opens the standard mortgage route.
- Talk to a lender early. Not every lender offers chattel loans, so ask which CMHC route they will use.
- Check the home’s standards and condition. CMHC requires new prefabricated homes to meet applicable standards. Get an inspection for a resale home.
- Review the lease if the lot is rented. Read the fee, increase rules and park rules with a lawyer.
- Run the full monthly cost. Add the mortgage, site fee, property tax, insurance and heating in our mortgage payment calculator.
Comparing other options? See all 14 types of houses in Canada, or check the land transfer tax on a purchase with land.
Frequently asked questions
Can you get a mortgage on a manufactured home in Canada?
Yes. CMHC says prefabricated homes permanently affixed to the land and placed on a permanent foundation are eligible under its standard underwriting criteria and are secured by a traditional mortgage. Movable homes that are not permanently affixed can be financed with a chattel loan under CMHC Chattel Financing.
What is the difference between a mobile home and a manufactured home?
Statistics Canada defines a mobile home as a single dwelling built to be transported on its own chassis and capable of being moved on short notice. Manufactured home is a broader term for a home built in a factory and moved to the site, which may then be placed on a permanent foundation.
What is the maximum amortization for a CMHC-insured prefab or manufactured home?
CMHC Prefab Plus lists a maximum amortization period of 25 years, with a purchase price or lending value below $1,500,000 for homeowner loans.
How much is CMHC insurance on a $300,000 manufactured home?
With 5% down, the mortgage is $285,000 and the CMHC premium at 95% loan-to-value is 4.00%, or $11,400, which is usually added to the mortgage. With 10% down the premium is 3.10%, or $8,370.
Does the home need year-round access?
Under CMHC Prefab Plus, the property must be suitable and available for full-time, year-round occupancy and must have year-round vehicular access, including homes located on an island.
- Sources, checked November 2, 2026: CMHC: Prefab Plus (no date shown on page); CMHC: Mortgage loan insurance cost (published 2018-03-31); CMHC: Mortgage loan insurance FAQs (published 2018-03-31); FCAC: Saving for a down payment (modified 2025-10-15); Statistics Canada, Type of Dwelling Reference Guide, 2021 Census (updated April 27, 2022).
- Method: Premiums were calculated by script from CMHC’s published premium rates for a hypothetical $300,000 home and re-checked by direct multiplication. The price is an example, not a market average.
Important: This guide is general information, not financial, legal or real estate advice. CMHC says Prefab Plus details are subject to change, lenders set their own policies, and land-lease rules differ by province. Gizly is not affiliated with the CMHC. See our affiliate disclosure.
Keep reading


Compare before you switch
Rates and offers checked against each bank’s own page.
Send it to a friend, a family member or a coworker with the same question. It takes one tap.
How this page was made: Gizly uses AI tools to help research and draft its guides. Krish Paul, the editor, is responsible for what Gizly publishes. Spot an error? Tell us and we will fix it.