Can a Store Refuse Cash in Canada? Legal Tender and the $25 Coin Limit
Cash is legal tender in Canada, but that does not mean every business has to take it. The rules on what a store can refuse are short, and a few of them surprise people.
- Rules checked November 22, 2026
- By Krish Paul
- 7 min read
On this page
This guide covers what the Bank of Canada and the Currency Act actually say, the coin limits, how cash totals are rounded and which old bills no longer count.
The short answer
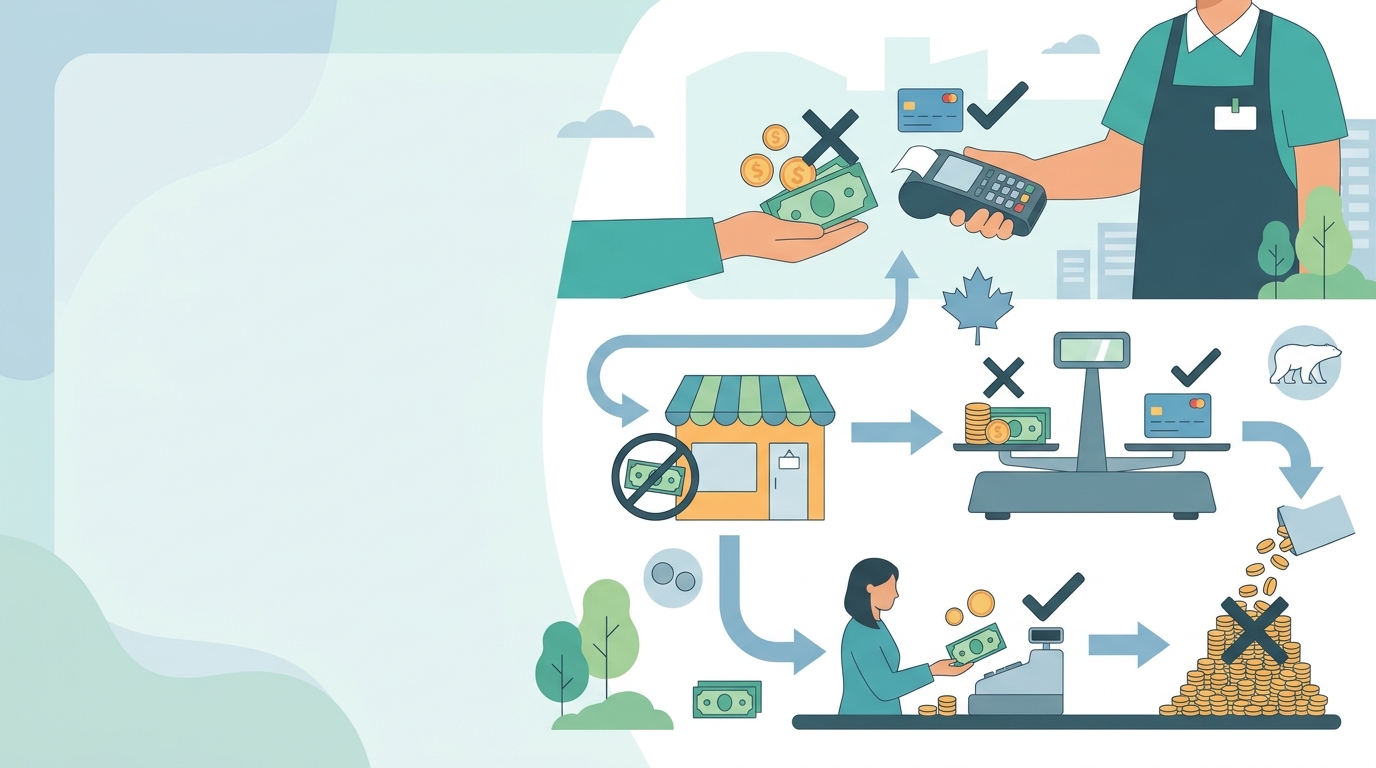
Yes, a store can refuse cash in Canada. The Bank of Canada says no law requires anyone to accept cash as a form of payment, and businesses have the right to choose how they are paid. A store can go card-only, refuse $100 or $50 bills, or turn away a big bag of coins.
That rule comes from the Bank of Canada. Legal tender still matters in a few narrow ways: the Currency Act caps how many coins count as legal tender in one payment, and five old bills have lost that status. If a business does take cash, it rounds the total to the nearest 5 cents.
What “legal tender” actually means
Bank of Canada bank notes and Royal Canadian Mint coins are legal tender. The Bank of Canada describes legal tender as the money approved in a country for paying debts. It is the official money, but the label does not force anyone to take it at the till.
The Bank of Canada puts it plainly: anything can be used as a form of payment if the buyer and seller agree to it. So the practical question is always what the business is willing to take. If you only have cash, ask before you order, book or fill up.
How many coins a store has to accept
Section 8 of the Currency Act sets a ceiling on coins. Above these amounts, a payment in that coin is not legal tender, and the business can refuse the extra coins. It can still accept more if it wants to.
| Coin | Legal tender up to | Coins at that limit |
|---|---|---|
| Toonie ($2), and $5 or $10 coins | $40 | 20 toonies |
| Loonie ($1) | $25 | 25 loonies |
| 50-cent and 25-cent coins | $10 | 40 quarters |
| Dime (10 cents) | $10 | 100 dimes |
| Nickel (5 cents) | $5 | 100 nickels |
| Penny (1 cent) | 25 cents | 25 pennies |
Source: Currency Act, section 8(2), current to October 29, 2026. Coin counts by Gizly. For a coin worth more than $10, only one coin counts as legal tender in a payment.
So if you try to pay a $30 bill entirely in loonies, you are over the $25 limit for that coin, and the business does not have to take them. Paying $30 with 15 toonies is fine, since it is under the $40 limit for $2 coins. Rolled coins for a bank deposit are a different matter, so ask your bank how it handles them.
Several payments on the same day count as one
The Act closes the obvious workaround. If one person owes another several amounts on the same day, the total is treated as one amount. You cannot split a bill into three small payments to push $60 of loonies through under the $25 limit.
How cash totals are rounded
The Royal Canadian Mint stopped distributing pennies on February 4, 2013. Since then, cash totals are rounded to the nearest 5 cents. The government release sets out the pattern: totals ending in 1, 2, 6 and 7 cents round down, those ending in 3, 4, 8 and 9 round up, and 0 and 5 stay the same.
Two details matter. First, the Canada Revenue Agency says rounding happens only after tax is added, so GST or HST is worked out on the exact price. Second, rounding applies only to cash. Cheques and electronic payments, including debit and credit cards, are charged to the cent.
Here is a hypothetical example. Your total after tax is $12.47. Pay cash and you hand over $12.45, because 7 rounds down. Tap a card and you pay $12.47. If the total were $12.48, cash would cost $12.50 and the card $12.48. Across all ten possible endings, the ups and downs cancel out: the average change is zero.
Pennies themselves still work. The government said the penny keeps its value indefinitely and can be used in cash transactions with businesses that choose to accept them. Under the coin limits above, though, only 25 cents in pennies is legal tender in one payment.
Bills that are no longer legal tender
As of January 1, 2021, the $1, $2, $25, $500 and $1,000 bills from every Bank of Canada series are no longer legal tender. A store can refuse them. They are not worthless, though. The Bank of Canada says they keep their face value and it will continue to honour them.
To cash one in, take it to your financial institution or send it to the Bank of Canada for redemption.
Before you head out with only cash
A few minutes of checking saves an awkward moment at the till.
- Ask firstIf a sign or website says “card only,” the business is within its rights. Ask before you order or pump gas.
- Carry smaller billsA business that takes cash can still turn down a $50 or $100 bill. Smaller bills give you the best chance.
- Keep coins modestStay under the Currency Act limits, or ask whether the business will take a larger amount in coins.
What could change: Bill S-8
A federal bill now before Parliament would add a new limit on large cash payments. The summary of Bill S-8 says it would stop certain persons or entities from accepting cash payments, donations or deposits of $10,000 or more. It is a proposal, not law. As of November 17, 2026 it was at second reading in the Senate and had not received royal assent. Our Bill S-8 explainer covers the details.
None of this affects everyday purchases. If you are carrying large amounts across the border, a separate reporting rule applies, covered in how much cash you can bring across the border.
What to do if a business will not take your cash
- Ask what it does accept. If it adds a fee for paying by credit card, check when stores can charge a credit card fee.
- Offer smaller bills or fewer coins. A business that takes cash may still refuse a large bill or a pile of coins.
- Get cash out ahead of time, or swap big bills at your bank. Check your card’s daily ATM withdrawal limit before a large cash purchase.
- Redeem retired bills. Take old $1, $2, $25, $500 or $1,000 bills to your bank or credit union, or mail them to the Bank of Canada.
- Raise it with the business, not a regulator. Since no law requires cash acceptance, a complaint is a customer service matter. Leave feedback or shop elsewhere.
Frequently asked questions
Can a store legally refuse cash in Canada?
Yes. The Bank of Canada says there is no law that requires anyone to accept cash as a form of payment, and businesses have the right to choose how they wish to be paid. A business can go cashless or refuse certain bills.
Can a store refuse a $100 bill?
Yes. Because a business can choose how it is paid, it can decline large bills. A $100 bill is still legal tender and keeps its value, so you can try another business or ask your bank for smaller bills.
How many coins can you pay with in Canada?
Under section 8 of the Currency Act, coins are legal tender only up to set amounts: $40 in coins of $2 to $10, $25 in loonies, $10 in coins from 10 cents to under $1, $5 in nickels and 25 cents in pennies. A business can accept more if it chooses.
Are old $1 and $2 bills still worth anything?
Yes. Since January 1, 2021, the $1, $2, $25, $500 and $1,000 bills are no longer legal tender, but the Bank of Canada says they keep their face value. You can redeem them at your financial institution or by sending them to the Bank of Canada.
Do stores round card payments to the nearest 5 cents?
No. Rounding applies only to cash payments, and only to the final total after tax. Debit, credit, cheque and other electronic payments are charged to the exact cent.
- Sources, checked November 22, 2026: Bank of Canada: About legal tender (modified 2026-10-14); Currency Act (R.S.C. 1985, c. C-52), current to 2026-10-29, sections 7 and 8; Government of Canada and Royal Canadian Mint: penny phase-out release (February 4, 2013); CRA: Phasing out the penny, tax implications for consumers; openparliament.ca: Bill S-8 (45-1) status and summary.
- Method: Coin counts are each Currency Act limit divided by the coin’s value, worked in cents. The rounding pattern was computed by script for all ten endings and matched against the government’s published rule. Examples are hypothetical.
Important: This guide is general information, not legal or financial advice. A business’s own payment policy decides what it accepts. Gizly is not paid by any business or bank mentioned here. See our affiliate disclosure.
Send it to a friend, a family member or a coworker with the same question. It takes one tap.
How this page was made: Gizly uses AI tools to help research and draft its guides. Krish Paul, the editor, is responsible for what Gizly publishes. Spot an error? Tell us and we will fix it.
Keep reading
Compare before you switch
Rates and offers checked against each bank’s own page.