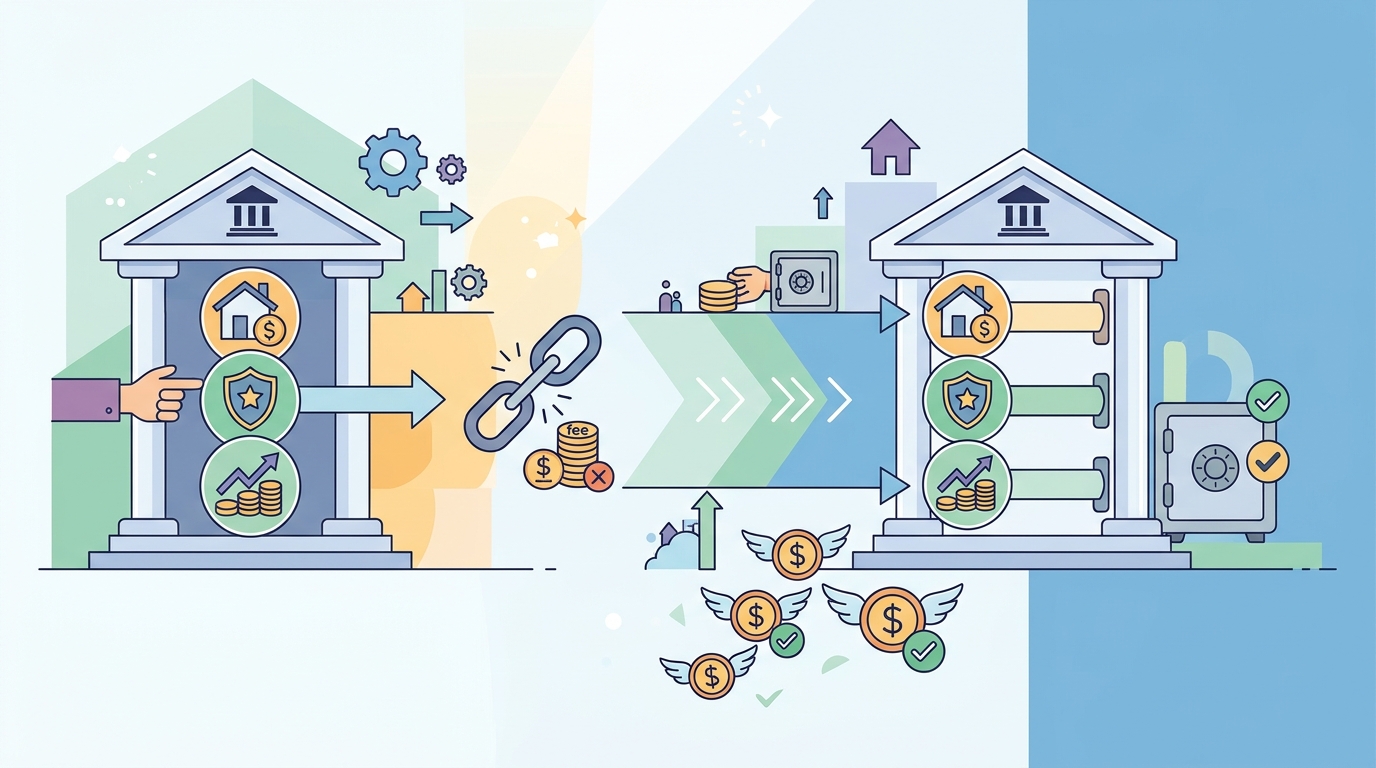
Ottawa Moves to Ban Bank Fees for Transferring RRSPs, TFSAs and Investment Accounts
Banks would no longer be able to charge you to move an RRSP, TFSA or other investment account to a competitor. The rules are a draft, and the ban does not reach bank-owned brokerages.
- Checked against Finance Canada and FCAC, November 5, 2026
- By Krish Paul
- 5 min read
On this page
The Department of Finance released draft regulations on Wednesday, November 4, 2026, that would stop federally regulated banks from charging fees to close or transfer investment accounts. The proposal delivers on a Budget 2025 promise from Finance Minister François-Philippe Champagne.
What the draft rules would do
The proposed regulations amend the Financial Consumer Protection Framework Regulations under the Bank Act. The core rule is short: a bank “must not impose a charge for the closing or transfer, including the partial transfer, of an investment account.”
- Accounts covered: registered accounts such as RRSPs, TFSAs and RESPs, and non-registered investment accounts.
- Partial transfers count. Moving part of an account would also be free.
- One exception: a bank could still charge if it gets the request less than 90 days after the account was first funded.
- Faster transfers: the bank you are leaving would have two clearing days to send an asset list, and the transfer would have to settle within 10 clearing days.
- Clear information: banks would have to post transfer information on a webpage reachable from their main site and provide it in print at no charge.
The Financial Consumer Agency of Canada would enforce the ban, according to The Logic.
Nothing changes yet. These are draft regulations. The fee ban would start 60 days after the final version is registered, and Finance has not set a date. Its cost analysis assumes January 1, 2027 for planning purposes only.
The big catch: bank-owned brokerages are not covered
The rules apply only to investment accounts held at banks, authorized foreign banks and federal credit unions. The draft says they “would not apply to investment accounts held at provincially regulated investment dealers, including investment dealer subsidiaries of banks.”
That matters if you hold an RRSP or TFSA through a bank’s brokerage or wealth arm that is set up as a separate, provincially regulated dealer. If your account sits there, the federal ban would not stop that dealer from charging you. Fintechs Canada said it wants to work with the provinces to extend the same protection.
What transfer fees cost today
In research published October 23, 2026, the Financial Consumer Agency of Canada found banks charge $50 to $150 per account to move all assets out of a registered product, and $25 to $75 per request for a partial transfer. The fee is charged for each account, whatever the balance.
FCAC concluded that transfer-out fees “can discourage account switching and weaken competitive pressure.” Budget 2025 put the average at $150 per account. Some receiving firms reimburse the fee, often in limited-time promotions or above a minimum balance.
How much it would save
Finance’s own estimate is modest. Its analysis says about 17,000 account transfers would be covered in the first year. It expects consumers to avoid $8.6 million in transfer fees over 10 years in present value, or about $1.1 million a year.
The department says the main benefit is more competition, which it did not put a dollar figure on. Counting only the measured items, it estimates a net cost of $6.2 million over 10 years, mostly fee revenue banks would give up.
Wealthsimple’s $73 million figure
Wealthsimple CEO Michael Katchen gave a much larger number. In a LinkedIn post quoted by iPhone in Canada and Fintech.ca, he wrote:
“This year alone, Canadians have been charged $73 million in exit fees to move their savings to Wealthsimple.”
Michael Katchen, CEO of Wealthsimple
The two figures measure different things. Katchen’s counts fees charged on transfers into one company. Finance’s counts only accounts the draft would cover, which leaves out bank-owned dealers. Katchen called transfer fees a “tax on choice” and said Wealthsimple has never charged an exit fee.
“Canadians should not be charged to move their own money. Moreover, exit fees can be a strong disincentive to switching, curtailing competition.”
Adriana Vega, executive director, Fintechs Canada
When it would take effect
| What changes | Takes effect after final rules are registered |
|---|---|
| No fees to close or transfer an investment account | 60 days |
| Transfer information on bank websites and in print | 12 months |
| GICs and similar products re-registered within 3 business days | 12 months |
| Transfers settled within 10 clearing days | 2 years |
Source: draft Investment Account Transfer Regulations, section 7 and the Regulatory Impact Analysis Statement. No registration date has been set.
The draft gives the industry two years for the 10-day transfer timeline so the Canadian Investment Regulatory Organization can build a technology fix. Budget 2025 had promised the drafts by spring 2026, so they arrived later than planned.
What it means for you
- Planning to move an account now? The ban is not in force. Ask the receiving firm whether it reimburses transfer-out fees, and get the terms in writing.
- Check who holds your account. Your statement shows whether it is the bank itself or a bank-owned investment dealer. Only accounts at the bank would be covered.
- New account? A fee could still apply if you move it within 90 days of first funding it.
- Want to weigh in? The draft lists Mark Radley, Director of Consumer Affairs at Finance Canada, as the contact for public enquiries at consumer.consommation@fin.gc.ca.
Frequently asked questions
Has Canada banned investment account transfer fees?
Not yet. The Department of Finance released draft regulations on November 4, 2026. The fee ban would start 60 days after the final regulations are registered, and no date has been set.
Which accounts would the transfer fee ban cover?
Investment accounts at banks, including registered accounts such as RRSPs, TFSAs and RESPs, and non-registered accounts. Partial transfers are covered too.
Does the ban apply to bank-owned brokerages?
No. The draft says the rules would not apply to investment accounts held at provincially regulated investment dealers, including investment dealer subsidiaries of banks.
How much do banks charge to transfer an RRSP or TFSA now?
The Financial Consumer Agency of Canada found fees of $50 to $150 per account to transfer everything out of a registered product, and $25 to $75 per request for a partial transfer.
Can a bank still charge a fee on a new account?
Yes. Under the draft, a bank could still charge if it receives the closing or transfer request less than 90 days after the account was first funded.
- Sources, checked November 5, 2026: Department of Finance Canada: Proposed Regulations Amending the Financial Consumer Protection Framework Regulations (Investment Account Transfers) and Regulatory Impact Analysis Statement; FCAC: Transfer-out fees (modified 2026-10-23); Department of Finance Canada: Budget 2025 introduces measures to promote competition and affordability (2025-11-06); The Logic: Ottawa moves to ban transfer fees for switching banks (2026-11-04); iPhone in Canada: Wealthsimple says Ottawa is finally banning the fee to leave your bank (2026-11-05); Fintech.ca: Fintechs welcome Ottawa’s proposed ban on investment transfer fees (2026-11-05).
- Method: Rules, dates and cost figures come from the draft regulations and Finance Canada’s impact analysis. Fee ranges come from FCAC. Quotes from Wealthsimple and Fintechs Canada are as reported by iPhone in Canada and Fintech.ca. We will update this story when the final rules are published.
Important: This story is general information, not financial or legal advice. The regulations are a draft and can change before they take effect. Gizly is not paid by any company mentioned here. See our affiliate disclosure.
Keep reading
Compare before you switch
Rates and offers checked against each bank’s own page.
Send it to a friend, a family member or a coworker with the same question. It takes one tap.
How this page was made: Gizly uses AI tools to help research and draft its guides. Krish Paul, the editor, is responsible for what Gizly publishes. Spot an error? Tell us and we will fix it.